
Oil and Gas Upstream Equipment Industry Set to Reach USD 110.89 Billion by 2035 as Digitalization and Efficient Drilling Reshape Upstream Operations
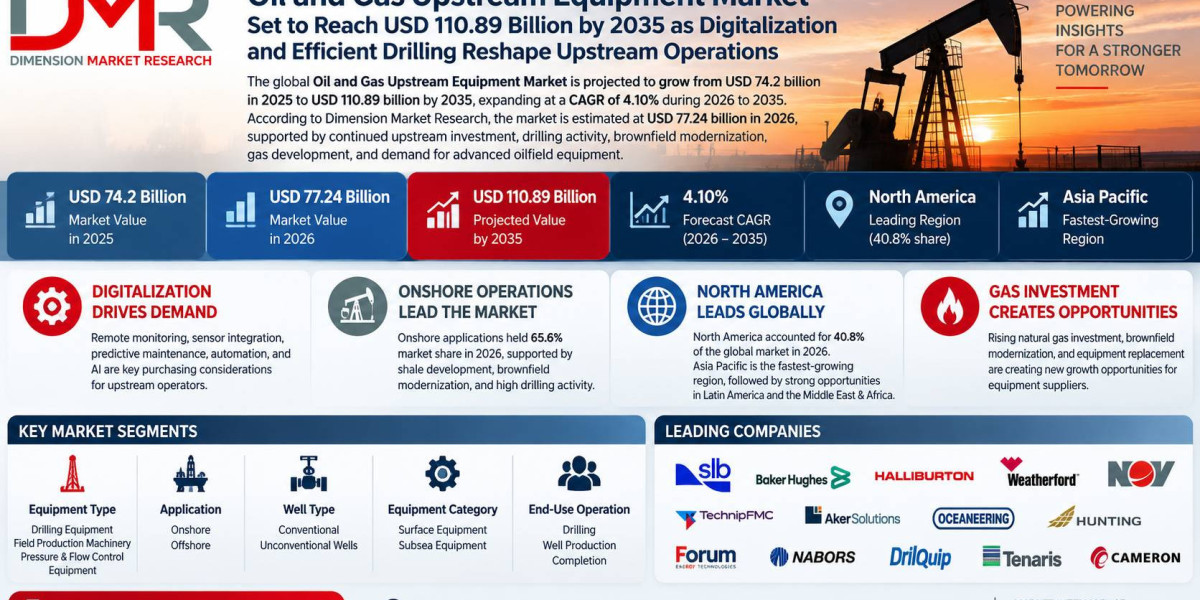
The global Oil and Gas Upstream Equipment Industry is projected to grow from USD 74.2 billion in 2025 to USD 110.89 billion by 2035, expanding at a CAGR of 4.10% during 2026 to 2035. According to Dimension Market Research, the market is estimated at USD 77.24 billion in 2026, supported by continued upstream investment, drilling activity, brownfield modernization, gas development, and demand for advanced oilfield equipment.
The market covers equipment used throughout exploration, drilling, well completion, production, pressure control, and related upstream operations. Key product categories include drilling systems, wellhead equipment, production machinery, pressure and flow control equipment, surface equipment, subsea equipment, and drilling waste management systems.
Oil and Gas Upstream Equipment Industry Outlook
The Oil and Gas Upstream Equipment Industry is being shaped by a shift from equipment volume toward equipment productivity. Operators are increasingly seeking drilling and production systems that deliver greater output, improved reliability, lower downtime, digital connectivity, and stronger environmental performance.
Drilling equipment remains the leading equipment type, accounting for 40.2% of market share in 2026. Onshore applications dominate with a 65.6% share, while conventional wells represent 59.8% of demand. Surface equipment holds a 57.8% share, and drilling operations account for 44.7% of end-use demand.
- Market value in 2025: USD 74.2 billion
- Market value in 2026: USD 77.24 billion
- Projected 2035 value: USD 110.89 billion
- Forecast CAGR: 4.10%
- Leading region: North America
- Fastest-growing region: Asia Pacific
Get free sample PDF of the Report - https://dimensionmarketresearch.com/request-sample/oil-gas-upstream-equipment-market/
Digitalization Drives Oilfield Equipment Demand
Digital transformation is becoming a major purchasing consideration for upstream operators. Equipment procurement is increasingly evaluated alongside remote monitoring, sensor integration, predictive maintenance, automation, and artificial intelligence capabilities.
The move toward connected equipment creates opportunities for manufacturers that can combine mechanical performance with digital intelligence. Operators are looking beyond traditional specifications and increasingly considering equipment lifecycle performance, predictive maintenance capability, operational visibility, and integration with digital oilfield platforms.
Automation is particularly important in drilling operations. Advanced drilling systems can improve connection times, casing performance, operational consistency, and workforce efficiency. This trend is encouraging oilfield equipment manufacturers to develop automation-ready drilling rigs, intelligent control systems, and digitally integrated production equipment.
Onshore Operations Maintain Market Leadership
Onshore applications held the largest share of the Oil and Gas Upstream Equipment Industry at 65.6% in 2026. The large installed base of producing wells, frequent drilling programs, and ongoing brownfield workovers support recurring demand for drilling rigs, wellhead systems, production equipment, and pressure control systems.
North American shale operations remain an important source of equipment demand. Established producing regions such as the Permian Basin, Eagle Ford, Haynesville, and Marcellus continue to require equipment for drilling, completion, production optimization, and field modernization.
Offshore operations represent a significant growth opportunity. Deepwater projects in Guyana, Brazil, West Africa, and other emerging offshore regions require specialized subsea equipment, wellheads, risers, blowout preventers, and offshore drilling systems. Although offshore equipment represents a smaller volume than onshore equipment, its higher unit value can create attractive opportunities for specialized suppliers.
North America Leads the Global Market
North America accounted for 40.8% of the global Oil and Gas Upstream Equipment Industry in 2026, representing approximately USD 30.27 billion. The region benefits from extensive unconventional oil and gas development, established infrastructure, high drilling activity, and continuous investment in production efficiency.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period. Demand is supported by offshore gas development in Australia, deepwater exploration in Malaysia and Indonesia, and unconventional gas development in China.
Latin America is also emerging as an important opportunity, particularly through deepwater activity in Guyana and Brazil. Meanwhile, the Middle East and Africa Oil and Gas Upstream Equipment Industry benefits from large-scale national oil company investment programs and long-term conventional oil and gas production requirements.
- North America leads with a 40.8% share
- Asia Pacific is the fastest-growing region
- Guyana and Brazil support offshore demand
- Middle East investment supports conventional equipment
- Europe remains focused on mature-field activity
Gas Investment Creates New Growth Opportunities
The upstream investment outlook is increasingly differentiated between oil and natural gas. Rising natural gas investment is creating opportunities for equipment suppliers serving gas production, compression, processing, stimulation, and related infrastructure.
This shift favors manufacturers with product portfolios that can support both oil and gas applications. Equipment suppliers capable of serving multiple upstream environments can reduce exposure to fluctuations in individual commodity investment cycles.
At the same time, strict capital discipline is limiting some new equipment purchases. Operators are prioritizing projects with strong returns and increasingly favoring equipment that improves production from existing assets. This makes brownfield modernization, equipment replacement, retrofit solutions, and aftermarket services important growth areas.
Predictive Maintenance and AI Reshape Equipment Procurement
Predictive maintenance is becoming a major factor in upstream equipment strategies. Sensor-enabled equipment and machine learning systems can help operators identify potential failures before they cause costly downtime.
As digital technologies mature, equipment manufacturers are increasingly expected to provide sensor-ready hardware and connectivity options as standard features. This creates an opportunity for vendors that can combine equipment manufacturing with monitoring, analytics, maintenance, and lifecycle services.
The competitive landscape is also changing. Major oilfield service and equipment companies are expanding their portfolios through acquisitions and integrated technology offerings. This trend is increasing competition while encouraging customers to consolidate procurement across equipment, services, software, and production optimization.
Competitive Landscape and Market Opportunities
The global market includes major companies such as SLB, Baker Hughes, Halliburton, Weatherford International, National Oilwell Varco, TechnipFMC, Aker Solutions, Oceaneering International, Hunting PLC, Forum Energy Technologies, Nabors Industries, DrilQuip, Tenaris, and Cameron International.
Competition is increasingly centered on integrated solutions rather than individual hardware products. Large suppliers benefit from global service networks, engineering capabilities, established customer relationships, and broader product portfolios.
However, specialized suppliers can find attractive opportunities in subsea systems, high-pressure and high-temperature equipment, drilling waste management, digital monitoring, artificial lift, automation, and specialized well completion technologies.
Key Market Segments
The Oil and Gas Upstream Equipment Industry report covers major segments across equipment, application, well type, equipment category, and end-use operation.
- Equipment Type: Drilling Equipment, Field Production Machinery, Pressure and Flow Control Equipment
- Application: Onshore and Offshore
- Well Type: Conventional and Unconventional Wells
- Equipment Category: Surface and Subsea Equipment
- End-Use Operation: Drilling, Well Production, and Completion
Report Also Cover
What is the Oil and Gas Upstream Equipment Industry size?
The global market is valued at USD 74.2 billion in 2025 and is estimated to reach USD 110.89 billion by 2035 at a 4.10% CAGR.
What is driving the Oil and Gas Upstream Equipment Industry?
Key growth factors include upstream production, drilling activity, brownfield modernization, gas investment, automation, digitalization, and demand for higher equipment efficiency.
Which equipment type dominates the market?
Drilling equipment leads the equipment type segment, accounting for 40.2% of the market in 2026.
Which application has the largest market share?
Onshore operations dominate with a 65.6% share of the market in 2026.
Which region leads the upstream equipment market?
North America is the leading regional market, holding a 40.8% share in 2026.
Which region is growing fastest?
Asia Pacific is projected to be the fastest-growing regional market during the forecast period.
Why is drilling equipment in high demand?
Drilling equipment is essential for new wells, workovers, recompletions, and upstream development programs, making it a core equipment category.
How is digitalization affecting oilfield equipment?
Digital monitoring, automation, predictive maintenance, and artificial intelligence are increasing demand for connected and sensor-enabled equipment.
What are the major opportunities for equipment manufacturers?
High-growth opportunities include subsea equipment, gas-related equipment, drilling automation, predictive maintenance, brownfield upgrades, and specialized completion technologies.
Who are the major companies in the market?
Major participants include SLB, Baker Hughes, Halliburton, Weatherford, National Oilwell Varco, TechnipFMC, Aker Solutions, Oceaneering International, Hunting PLC, and other global equipment and oilfield technology providers.
Related Report:
- Middle East Oil & Gas Monitoring System Market
- Middle East Oil & Gas Pipeline Infrastructure Market
- Oil and Gas Line Pipe Market
- Oilfield Chemicals Market
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA: +17323699777
Phone India: +919310023843
E-mail: enquiry@dimensionmarketresearch.com
Address USA: 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India: D44, Sector 6, Noida 201301, India